

Competitive premiums
Our key cover is designed to be affordable whilst providing comprehensive protection for your household keys.
Add key cover for extra help if your keys are lost, stolen or damaged.
When you choose to include key cover with your Policy Expert home insurance, you benefit from:
Our key cover is designed to be affordable whilst providing comprehensive protection for your household keys.

Our claims team works efficiently to get your claim processed without unnecessary delays.

You can tailor your protection to match your specific needs and circumstances.
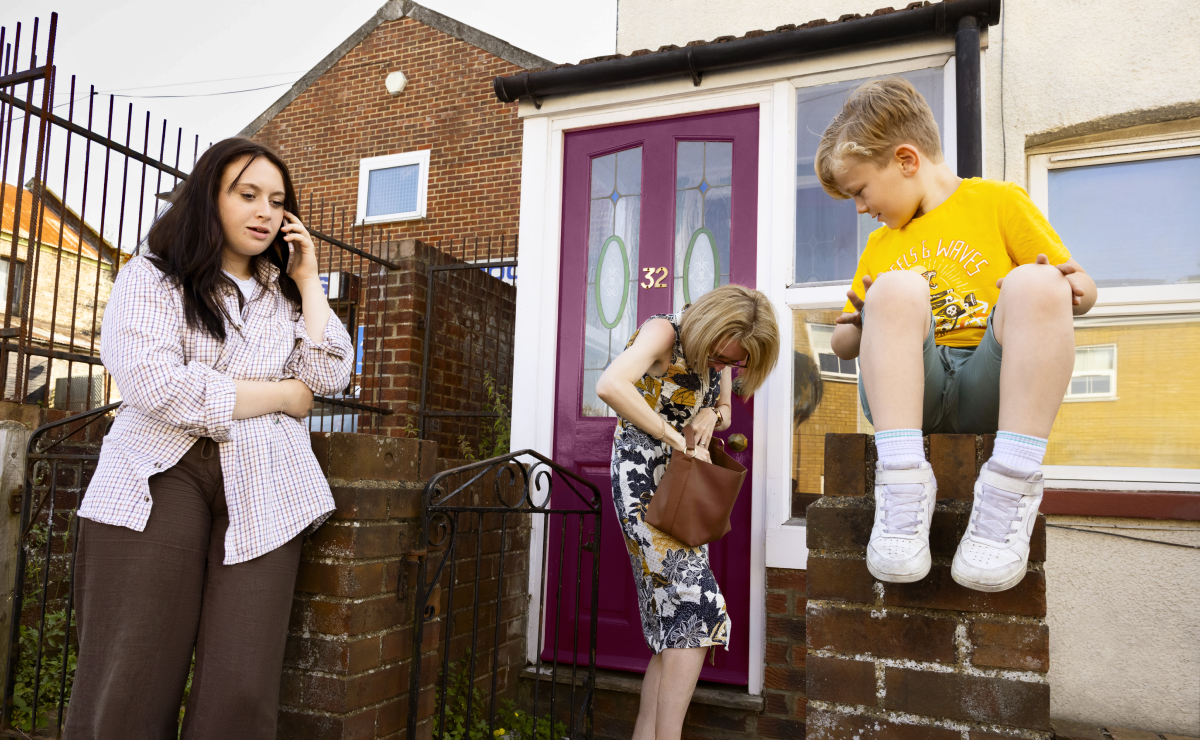
Key cover insurance is a specialist policy that protects you against the financial costs associated with lost, stolen, or damaged keys. It’s designed to cover the expenses you’d face if you suddenly found yourself unable to access your home.
If you lose or have your keys stolen in the UK, you're covered for replacing your locks and keys. Depending on your policy, this could also include outbuilding keys, such as those for your shed or garage.
If you choose to add our key cover extra to your policy, you will be covered for the following:

if you can’t use your car because of lost or stolen keys.
if a covered key incident leaves you unable to drive, we’ll pay to take you, your vehicle or both to your destination, somewhere you can collect a spare key, a garage or your home.
if an insured key is broken
so you will receive the full amount of your claim.
Can’t find your documents? Give us a ring. We can quickly confirm what’s included in your policy and explain what key cover would add.


To make a claim on your key cover, call our key cover phone number: 0330 0600 623
Lines are open 24 hours a day. Please quote your Keycare fob number when you call. Keep a record of it separately from your keys in case they go missing.
When you choose Policy Expert, you're choosing an insurer recognised for great customer service.
We are rated Excellent on Trustpilot. and were named Buildings Insurance Provider of the Year in the Telegraph Insurance Awards 2025.
If a key attached to your registered Keycare fob is lost, stolen or locked inside your home or vehicle, key cover can pay for eligible locksmith charges, replacement keys and new locks. Broken keys are covered up to £50 per claim. There’s no excess, and the overall limit is £1,500 per period of insurance. The policy also includes vehicle hire and onward transport in certain circumstances. Limits and exclusions apply.
If you find your keys after making a claim, contact us and let us know. We can explain what this means for your claim.
If your keys go missing, check places you may have left them, such as your pockets, bag or car, and report the loss to Keycare as soon as possible.
A key safe can be a practical solution for preventing lockouts. However, key safes aren’t without risks. Security experts warn that cheaper models can be vulnerable to forced entry, and if someone discovers your safe’s location and code, they have direct access to your home.
If you do opt for a key safe, invest in a high-quality model with a police-approved rating. Mount it in a discreet location rather than obviously next to your front door and change the combination regularly. A key safe doesn’t replace the need for key cover insurance-you might still lose keys elsewhere or need locks changed for other reasons.
Keyless entry systems, including smart locks and electronic keypads, are becoming increasingly popular. They eliminate the risk of lost keys entirely, as you can access your property using a code, fingerprint, or smartphone app. This technology offers genuine convenience; you’ll never find yourself locked out because you forgot your keys.
That said, keyless systems come with their own considerations. They require power (usually batteries or mains electricity), and technical failures do occasionally happen. There’s also the initial installation cost, which can be significant for quality systems. Some insurers have specific requirements for keyless entry systems, so check your home insurance policy before making the switch.
Even with a keyless system, you might still want key cover if you maintain traditional locks on outbuildings or if your system includes a physical key override option.
Cover for unexpected accidents that damage your contents.
Find out what Policy Expert home emergency cover includes, what's covered, and how it can help when things go wrong.
Learn what Policy Expert legal expenses cover includes, the types of disputes it can help with, and when you can make a claim.